Refund for Unregistered Taxpayers
Refund for unregistered taxpayers helps eligible individuals obtain a refund of GST paid in specific circumstances, such as certain property transactions where the agreement is cancelled. My Startup Solution assists with eligibility checks, document preparation, refund application filing, and follow-up based on applicable GST rules.
Whats Included
- ✓ Preliminary GST refund eligibility assessment and transaction review
- ✓ Document checklist and verification of invoices, payment receipts, and cancellation records.
- ✓ Assistance with temporary GST registration and FORM GST RFD-01 preparation.
- ✓ Assistance with temporary GST registration and FORM GST RFD-01 preparation.
Get Free Expert Consultation
Refund for Unregistered Taxpayers
The GST law provides a specific refund mechanism for eligible unregistered buyers in prescribed circumstances. However, th...
Individuals who are not registered under the Goods and Services Tax (GST) system may still qualify for a GST refund in certain situations. One important example is when a person pays GST to a property developer for an under-construction property, but the agreement is cancelled and the developer refunds the amount paid for the property without returning the applicable GST.
The GST law provides a specific refund mechanism for eligible unregistered buyers in prescribed circumstances. However, the refund is subject to applicable conditions, documentation requirements, and filing deadlines. Understanding these requirements before submitting an application can help avoid incomplete filings and unnecessary delays.
A refund for unregistered taxpayers is a service that helps eligible individuals understand the applicable rules, check their documents, prepare a refund application, and manage the filing process. My Startup Solution provides assistance based on the transaction details and the requirements applicable to the individual case.
What Is a GST Refund for Unregistered Taxpayers?
A GST refund for an unregistered taxpayer is a refund of eligible GST paid by a person who does not hold GST registration, where the law specifically permits the refund.
Under Section 54 of the Central Goods and Services Tax (CGST) Act, 2017, read with the relevant rules, refunds may be available to unregistered persons in prescribed circumstances. A common example involves the cancellation of a contract or agreement for the supply of services or goods where the supplier has collected GST and the relevant conditions for refund are satisfied.
The refund mechanism is not available automatically for every GST payment made by an unregistered person. The transaction must fall within an eligible category, and the applicant must meet the applicable legal requirements.
Common Example: Cancellation of an Under-Construction Property Purchase
Suppose an individual books an under-construction flat and pays the developer an amount that includes GST. Later, the booking or agreement is cancelled, and the developer refunds the consideration but does not return the GST amount.
If the circumstances satisfy the applicable GST refund provisions, the buyer may be eligible to apply for a refund of the GST paid. The buyer must provide the required documents and submit the application within the prescribed time limit.
Other situations should be assessed individually because the availability of a refund depends on the nature of the transaction and the applicable GST provisions.
Who Can Apply for a Refund as an Unregistered Taxpayer?
This service may be useful for individuals who have paid GST but are not registered under GST and believe that their transaction qualifies for a refund.
Potential applicants may include:
- Individuals whose eligible property booking or purchase agreements have been cancelled.
- Buyers who paid GST to a supplier but did not receive the corresponding GST amount back after cancellation.
- Individuals who need help understanding whether their transaction falls within the unregistered-person refund provisions.
- Applicants who need assistance organising supporting documents and preparing the prescribed refund application.
Eligibility depends on the facts of the transaction, the applicable legal provisions, and the supporting evidence. Not every cancelled booking or commercial dispute qualifies for a GST refund.
Documents Required for a GST Refund Application
The required documents depend on the transaction and the reason for claiming the refund. For eligible unregistered taxpayers, the following documents may be relevant:
- PAN and identity details of the applicant.
- Address and contact information.
- Booking form, agreement, or other transaction documents.
- Payment receipts and bank statements showing the amounts paid.
- Tax invoices or other available evidence of GST payment.
- Cancellation letter or proof of cancellation.
- Refund statement or correspondence from the supplier.
- Bank account details and supporting bank documentation.
- Any declarations, undertakings, or additional documents required under the applicable procedure.
Applicants should ensure that the documents are consistent and that the GST amount claimed can be supported by available records. Additional information may be requested during processing.
GST Refund Application Process for Unregistered Persons
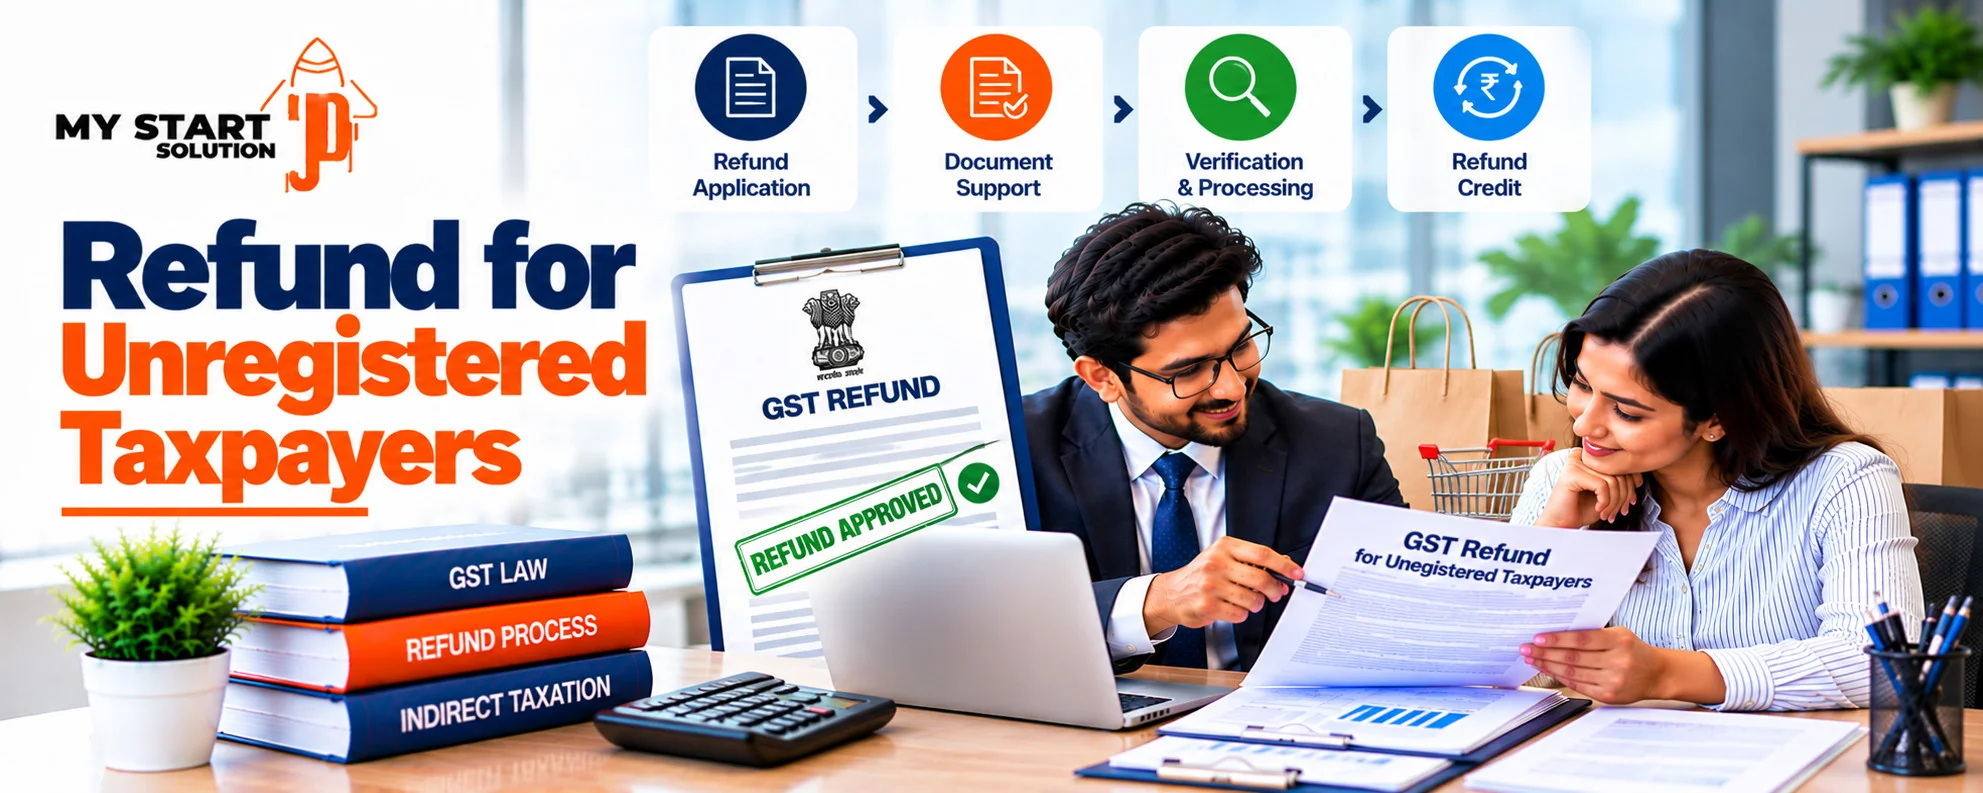
Eligible applicants generally apply online through the GST portal using FORM GST RFD-01 under the category “Refund for unregistered person.” The process involves obtaining the required temporary registration, preparing the prescribed information, and uploading supporting documents.
CBIC
+2
Step 1: Check Refund Eligibility
The transaction is reviewed to determine whether it qualifies under the applicable GST refund provisions. The agreement, payment details, cancellation records, and tax documents are examined before proceeding.
Step 2: Arrange Temporary Registration
An eligible unregistered applicant may need to obtain temporary GST registration on the portal to submit the refund application. The applicable registration and identity requirements should be checked before filing.
Step 3: Prepare the Refund Application
The relevant details are compiled in FORM GST RFD-01. Depending on the claim, the application may require prescribed statements, invoice details, a supplier's certificate, and evidence that the applicant paid and bore the tax.
Goods and Services Tax Council
+1
Step 4: Submit the Application and Track Its Status
After the application and supporting documents are submitted, the applicant can monitor its status and respond to any further information requests from the department. Approval depends on the eligibility conditions and assessment of the claim.
Important GST Refund Rules to Understand
Before applying for a refund as an unregistered taxpayer, consider the following points:
- Refund eligibility: The claim must fall within a category permitted under GST law. A cancelled transaction alone does not guarantee a refund.
- Supplier documentation: Certain claims require a certificate from the supplier confirming the relevant tax treatment and that the tax has not been adjusted or claimed again.
- Refund amount: The amount claimed must be supported by the relevant invoices and tax-payment records and must comply with applicable limits.
- Bank account requirements: Applicants must follow the prescribed identity and bank-account verification requirements.
- Filing deadline: Refund applications are subject to statutory time limits. The relevant date and applicable period should be verified for the specific claim before filing.
The applicable procedure may differ according to the transaction type, so the current GST rules and relevant departmental instructions should be checked before submission.
CBIC
+2
Why Choose My Startup Solution for GST Refund Assistance?
Applying for a GST refund without registration can involve unfamiliar portal requirements, supporting certificates, and detailed transaction records. Professional assistance can help applicants understand these requirements before submitting their claim.
My Startup Solution can assist with:
- Reviewing the transaction and preliminary refund eligibility.
- Preparing a checklist of required documents.
- Organising payment records, invoices, and cancellation evidence.
- Assisting with the refund application and relevant supporting information.
- Providing guidance on application tracking and departmental queries.
The scope of assistance depends on the case and the documents available. Refund approval and processing timelines remain subject to the applicable law and the GST department's decision.
When Should You Seek GST Refund Assistance?
Consider seeking professional assistance if your property booking has been cancelled, an eligible long-term insurance policy has been terminated, or you have paid GST on a transaction that may qualify for a refund under the applicable provisions.
It is useful to review the agreement, payment records, cancellation date, supplier correspondence, and tax invoices before starting the application. Early review can help identify missing documents and determine which filing procedure applies.
Conclusion
A GST refund for unregistered taxpayers may be available in specific circumstances, including certain cancelled property agreements and terminated long-term insurance policies. Applicants need to meet the applicable conditions and provide the required supporting evidence.
With appropriate documentation and procedural guidance, applicants can prepare a more complete refund application and understand the steps involved. My Startup Solution provides assistance with eligibility review, documentation, filing support, and follow-up for eligible GST refund claims.
Eligibility Criteria for Refund for Unregistered Taxpayers
- GST Registration Not Required: This refund facility may apply to individuals or businesses that are not registered under GST but have paid tax on certain transactions, such as an advance payment for services that were not supplied.
- Eligible Refund Situations: An unregistered taxpayer may be eligible to claim a refund when a service is cancelled or a contract is terminated and the supplier issues the required refund documentation.
- Valid Transaction Proof: Applicants should have supporting records, such as payment receipts, invoices, or other documents that establish the original transaction and the refund amount.
- Refund Claim Within the Prescribed Time Limit: The application must be filed within the applicable GST time limit, subject to the relevant rules and conditions.
- Compliance With GST Requirements: The claim must meet the applicable GST provisions, including the prescribed application procedure and supporting documentation.
Documents required
Documents Required to Claim a GST Refund for Unregistered Taxpayers
Registration process
A simple four-step process, start to finish.