MSME Loan Scheme
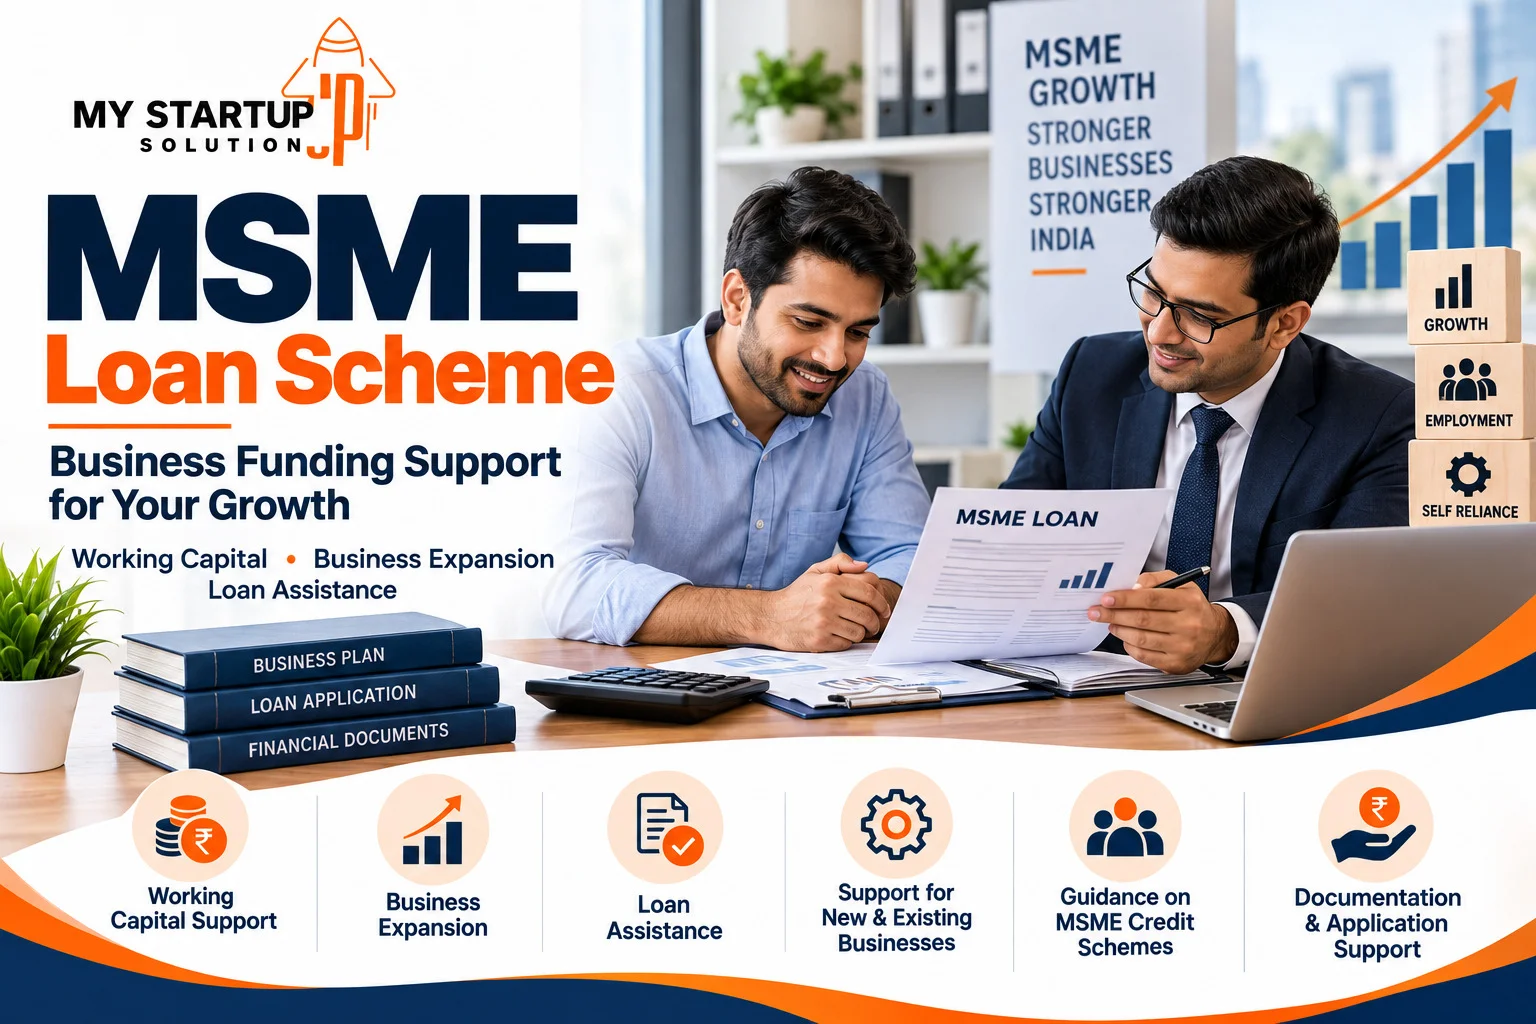
The MSME loan scheme helps eligible micro, small and medium businesses access finance for working capital, equipment, expansion, or business setup. My Startup Solution can help assess your requirements, identify suitable loan or credit-support options, and prepare the required documentation for the application process.
Whats Included
- ✓ MSME loan requirement and eligibility assessment
- ✓ Guidance on suitable MSME financing options
- ✓ Documentation and application preparation support
- ✓ Assistance with understanding scheme and lender requirements
Get Free Expert Consultation
MSME Loan Scheme
The right option depends on factors such as the type of business, business stage, funding requirement, repayment capacity, available do...
An MSME loan scheme can help eligible businesses arrange finance for starting, operating, or expanding their business. Depending on the business profile, funding requirement, eligibility, and lender, an MSME may explore options such as working capital finance, term loans, credit guarantee-backed facilities, MUDRA loans, or government-supported credit schemes.
The right option depends on factors such as the type of business, business stage, funding requirement, repayment capacity, available documents, and applicable scheme conditions. My Startup Solution can help businesses understand suitable financing options and organise the information required for the application.
What Is an MSME Loan Scheme?
An MSME loan scheme refers to financing options available to eligible micro, small, and medium enterprises through banks, financial institutions, and certain government-supported programmes.
The Ministry of MSME lists several credit-related schemes, including PMEGP and the Credit Guarantee Scheme through CGTMSE. Different schemes have different eligibility requirements, loan structures, application procedures, and benefits.
The current MSME classification, applicable from 1 April 2025, is based on investment in plant and machinery or equipment and annual turnover. The revised limits classify enterprises as micro, small, or medium according to the applicable investment and turnover thresholds.
Who Can Consider MSME Business Loans?
MSME finance may be relevant for businesses that need funds for genuine business purposes, subject to the eligibility criteria of the selected lender or scheme.
Common applicants may include:
- Manufacturing businesses
- Service providers
- Trading businesses
- New entrepreneurs
- Existing micro and small enterprises
- Businesses looking for working capital
- Enterprises planning expansion or equipment purchases
- Eligible businesses seeking government-supported credit facilities
Eligibility is not automatic. Banks and financial institutions generally assess the applicant's business profile, repayment capacity, financial information, credit history, documents, and other applicable criteria.
Common Purposes of MSME Financing
Businesses may require finance for different operational and growth requirements. Depending on the selected loan product, funds may be considered for:
Working Capital
Businesses may need working capital to manage regular expenses, inventory, supplier payments, receivables, and other operating requirements.
Machinery and Equipment
A term loan may be considered when a business needs to purchase or upgrade machinery, equipment, tools, or other business assets.
Business Expansion
Existing enterprises may require additional funds for increasing production capacity, opening another location, upgrading operations, or supporting business growth.
New Business Setup
Some government-supported programmes are designed specifically for eligible entrepreneurs establishing new micro-enterprises. For example, PMEGP is a credit-linked subsidy programme for setting up eligible new micro-enterprises in the non-farm sector.
Government-Linked MSME Loan Options
There is no single loan that applies to every MSME. Depending on the applicant and purpose, different government-supported options may be relevant.
PMEGP
The Prime Minister's Employment Generation Programme (PMEGP) provides credit-linked subsidy support for eligible new micro-enterprises. The current Ministry of MSME information specifies maximum admissible project costs of ₹50 lakh for manufacturing and ₹20 lakh for business or service projects, subject to scheme conditions.
CGTMSE Credit Guarantee
The Credit Guarantee Scheme operated through CGTMSE is designed to support lending to eligible Micro and Small Enterprises. Under the current CGTMSE scheme document, eligible lending institutions can obtain guarantee cover for qualifying credit facilities without collateral security and/or third-party guarantees, subject to the scheme's conditions and applicable limits.
A credit guarantee does not mean that every applicant receives a loan automatically. The lending institution still evaluates the borrower and makes the lending decision.
MUDRA Loans
The Pradhan Mantri MUDRA Yojana supports eligible micro enterprises engaged in income-generating activities such as manufacturing, trading, and services. The government describes the categories as Shishu, Kishor, Tarun, and Tarun Plus, with financing limits based on the applicable category and eligibility conditions.
Documents Commonly Required
The exact documentation depends on the lender, business structure, loan type, and applicable scheme. Applicants may commonly need:
- PAN and identity documents
- Address proof
- Business registration details
- Udyam Registration details, where applicable
- Bank account statements
- Income tax returns
- GST returns, where applicable
- Financial statements
- Business or project details
- Information about the proposed use of funds
- Existing loan or credit details
Additional documents may be requested during the lender's assessment.
How My Startup Solution Can Help
Choosing an MSME financing option can be difficult when different schemes have different requirements. My Startup Solution can assist with understanding the business requirement, reviewing basic eligibility factors, organising documents, and preparing the information needed for the application process.
Our assistance can include:
- Understanding the purpose and amount of finance required.
- Reviewing the business structure and available documentation.
- Identifying potentially relevant MSME financing or government-supported options.
- Helping organise the information and documents required for application.
- Supporting the application preparation process based on the applicable requirements.
The final approval, sanctioned amount, interest rate, repayment period, security requirements, and other lending terms are determined by the concerned bank, financial institution, or applicable scheme authority.
Why Choose the Right MSME Loan Option?
Selecting finance based only on the loan amount may not be suitable for every business. Entrepreneurs should also consider the purpose of borrowing, repayment capacity, total borrowing cost, tenure, security requirements, processing conditions, and scheme eligibility.
A suitable financing option should match the business's actual funding requirement and financial position.
Before applying, businesses should also keep their financial records and statutory registrations updated where applicable. Proper documentation can make it easier to present the business information required during lender assessment.
Get Assistance for an MSME Loan Scheme
Whether you are starting a small enterprise, managing working capital, purchasing equipment, or planning expansion, the appropriate financing route depends on your business circumstances.
My Startup Solution can help you understand the available MSME loan scheme options and prepare for the application process with relevant information and documentation. Since scheme rules and lender requirements can change, eligibility should always be checked against the latest applicable guidelines before applying.
Eligibility Criteria for MSME Loan Scheme
- Eligible MSME Business: The applicant should generally operate a micro, small, or medium enterprise that meets the applicable MSME classification criteria.
- Valid Business Registration: The business should have appropriate registration and identification documents, such as a valid Udyam Registration where applicable.
- Business Activity: The enterprise should carry out an eligible manufacturing, service, or trading activity as permitted under the selected MSME loan scheme.
- Repayment Capacity: Lenders may assess the business's income, cash flow, existing liabilities, and ability to repay the proposed loan.
- Credit Profile: The applicant's credit history and financial records may be considered while evaluating the loan application.
- Scheme-Specific Conditions: Eligibility can vary depending on the loan scheme, lender, loan amount, business type, and purpose of financing.
Documents required
Documents Required for MSME Loan Scheme
Registration process
A simple four-step process, start to finish.